A prescription or routine service can sometimes cost less outside the plan. Before paying cash, ask whether the expense will receive deductible or out-of-pocket credit under the current contract.
Austin health & life insurance broker
Insurance should solve a real problem.
Independent help for Austin individuals, families, self-employed professionals, and small businesses comparing health insurance, life insurance, final expense, income protection, and annuities. Clear options. Real tradeoffs. No pressure to buy more than makes sense.
Licensed Texas agentMultiple carriersEnglish / SpanishNo-obligation review
Start with the problem you already have
What are you trying to solve?
Start with what needs protecting. Then compare the options that fit your priorities, budget, and real-life risks.
Most searched locally
Individual & Family Health Insurance
Compare available health coverage, costs, provider-network considerations, deductibles, and enrollment paths in plain English.
Explore Austin health insurance →
Self-employed
Health Insurance When You Work for Yourself
Coverage decisions for consultants, 1099 professionals, independent contractors, and business owners without an employer plan.
See self-employed options →
Business owners
Small Business & Group Health Insurance
Evaluate whether group coverage, individual strategies, or a different benefit approach fits the business and employees.
Review business health options →
Family protection
Life Insurance
Term and permanent coverage decisions based on income replacement, debts, family obligations, and the amount of risk you want to retain.
Compare life insurance →
Simple objective
Final Expense Insurance
Smaller-face life insurance designed to help families prepare for funeral costs, final bills, and other end-of-life expenses.
Learn about final expense →
Income protection
Disability Income Insurance
For people who want to understand what it costs to transfer part of the risk of losing earned income due to sickness or injury.
Review income protection →
Retirement income
Annuities
Compare fixed, multi-year guarantee, indexed, immediate-income, and lifetime-income structures with liquidity and surrender tradeoffs clearly identified.
Explore annuity decisions →
Supplemental protection
Accident, Hospital & Critical Illness
Scheduled or event-specific cash benefits can help with retained medical and household costs—but they are not replacements for comprehensive major medical.
See how gap coverage fits →
Coverage has to fit real life
Your insurance budget does not exist in a vacuum.
Premiums compete with housing, groceries, debt, emergency savings, retirement, and everything else. A good recommendation has to survive that reality.
Right-size the riskCompare the tradeoffsKeep cash flow in viewSay no when it does not fit
“Should I buy this policy?” is not the first question. The first question is: “What happens financially if I do nothing?”
The healthcare buyer is changing
People want to own the savings—not lose them for shopping smarter.
More Americans are comparing cash prices, using virtual care or membership models, and asking whether consumer-owned health dollars can stretch further. That creates a new job for an insurance review: separate routine spending from the large risks a household cannot comfortably absorb.
Policy proposals remain proposals until enacted, and current plan and tax rules control. Perspective informed by “Let Americans Keep the Savings They Find”.
HSAs and FSAs reward deliberate spending, but eligibility and qualified-expense rules remain technical. Verify the current rules rather than assuming every plan or membership qualifies.
Price shopping can help with routine care. It does not replace protection against a hospitalization, major diagnosis, loss of income, or another event large enough to overwhelm savings.
Annuities & retirement income
A guarantee is useful only when the tradeoff is visible.
Annuities can help create principal guarantees, a defined interest period, or contractual income. They are not one product, and they should not be used as a generic answer for every retirement concern.
Declared-rate periods with surrender schedules, free-withdrawal provisions, renewal risk, and possible market-value adjustments.
Index-linked crediting without direct index ownership. Caps, participation rates, spreads, and crediting methods require review.
A premium becomes a selected payment stream. Liquidity, life contingency, refund features, and beneficiary treatment drive the decision.
A benefit base may calculate lifetime withdrawals without being the cash value available as a lump sum.
Annuities are long-term insurance contracts, are not FDIC insured, and may include surrender charges and tax consequences. Guarantees depend on the claims-paying ability of the issuing insurer. Current rates and illustrations must be verified.
The ABA carrier shelf
Multiple markets. Different verticals.
Carrier nameplates show the research lanes available through ABA. A carrier is part of the decision—not the decision by itself.
Names identify potential carrier markets researched by ABA and do not imply endorsement. Appointments, products, rates, underwriting, and Texas availability are verified before presentation. Approved carrier logos can replace these nameplates when authorized co-brand assets are available.
How the review works
Clarity before paperwork.
No carrier brochure is allowed to make the decision for you. We start with the risk, your budget, and the outcome you actually want.
1
Tell me what changed.
Lost employer coverage? Starting a business? Family protection? Final expenses? A new health-cost concern? Start there.
2
Separate needs from nice-to-haves.
We look at current coverage, savings, income, obligations, and the risk you can reasonably retain.
3
Compare the available options.
If insurance makes sense, compare carrier terms, costs, limitations, exclusions, and underwriting requirements.
4
Apply accurately.
Clear, truthful applications matter. No agent controls future underwriting or claims, so accuracy and documentation are non-negotiable.
What I will not promise
“Trust me, it will pay” is not advice.
No insurance agent controls a carrier's underwriting department or future claims decision. My job is to help you understand what you are buying, where the contract has limits, and whether the premium is worth the risk being transferred.
If a product does not meaningfully solve the problem you came in with, I would rather tell you that before you spend the money.
Real-world insurance questions
Would your policy pay?
Changes in healthcare, technology, work, and the economy can expose coverage gaps. ABA turns those changes into practical questions you can ask before a claim.
Accident • Technology
A driverless robotaxi hits you. Which policy responds?
Health coverage, accident coverage, and legal liability are different questions.
Claims • Trust
Three doctors say you cannot work. Can a disability claim still be denied?
A medical opinion and a policy's contractual definition are not always the same thing.
Economy • Risk
If money gets tight, which insurance premium still deserves a place?
Risk transfer has to compete with the rest of the household budget.
Insurance in real life
Six households. Six different audits.
These fictional examples show how ABA frames a decision. They are not quotes, guarantees, tax advice, or promises that a product will be available or pay a claim.
Health · Active pre-retiree
Meet Lena, 59
Lena is an Austin real estate agent with a high-deductible medical plan, healthy savings, and a weekend life built around cycling and hiking.
The concern
A serious fall could create deductible exposure, follow-up therapy, and weeks away from work at the same time.
The ABA audit path
Keep major medical as the foundation. Then compare the actual schedules and triggers of accident, hospital, or disability coverage against the gap Lena cannot comfortably self-fund.
Life · Young professional
Meet Evan, 30
Evan is a software developer earning $72,000. He has a car loan, helps his mother each month, and assumed life insurance could wait.
The concern
A recent highway accident made him realize that even without children, another person depends on his income and could inherit immediate expenses.
The ABA audit path
First calculate the actual obligation and time horizon. Then compare affordable term coverage, underwriting paths, and whether any accident or disability feature solves a separate risk without crowding out emergency savings.
Health · Price shopping
Meet Sofia and Daniel
Their family plan has a large deductible, and one recurring prescription costs less through a cash-pay program than through the plan.
The concern
The lower pharmacy price saves money today, but they do not know whether that spending receives credit toward the deductible or annual out-of-pocket limit.
The ABA audit path
Compare total annual cost—not premium alone. Confirm the plan’s cash-purchase rules, preserve receipts, review HSA eligibility under current rules, and keep catastrophic exposure separate from routine-care shopping.
Self-employed · Consumer-directed care
Meet Maya, 38
Maya runs a design studio and likes a direct-primary-care membership for routine visits, transparent pricing, and easier access.
The concern
The membership is not major medical, and pairing it with the wrong coverage or account strategy could leave an expensive gap or create an eligibility problem.
The ABA audit path
Identify what the membership includes, what it excludes, which major-medical path handles large claims, and whether current HSA or tax rules support the intended arrangement.
Business owner · Income protection
Meet Carlos, 47
Carlos owns a small engineering firm. His household needs his income, and the firm still owes rent, software subscriptions, and staff expenses if he cannot work.
The concern
One disability creates two different losses: Carlos’s personal paycheck and the business overhead that continues without him.
The ABA audit path
Compare individual disability income and business overhead expense as separate contracts. Audit occupation definition, residual benefits, eligible expenses, elimination period, and benefit duration.
Retirement · Annuity decision
Meet Renee, 63
Renee is retiring next year. A CD is maturing, she has Social Security and investments, and she wants part of her income to feel less dependent on market timing.
The concern
She wants guarantees but may need funds for home repairs or family support, so surrender and liquidity matter as much as the illustrated income.
The ABA audit path
Map essential income, liquid reserves, legacy priorities, and time horizon. Then compare fixed, MYGA, indexed, or immediate-income structures while separating cash value from any income-benefit base.
Independent guidance in Austin
Insurance is the tool. The decision comes first.
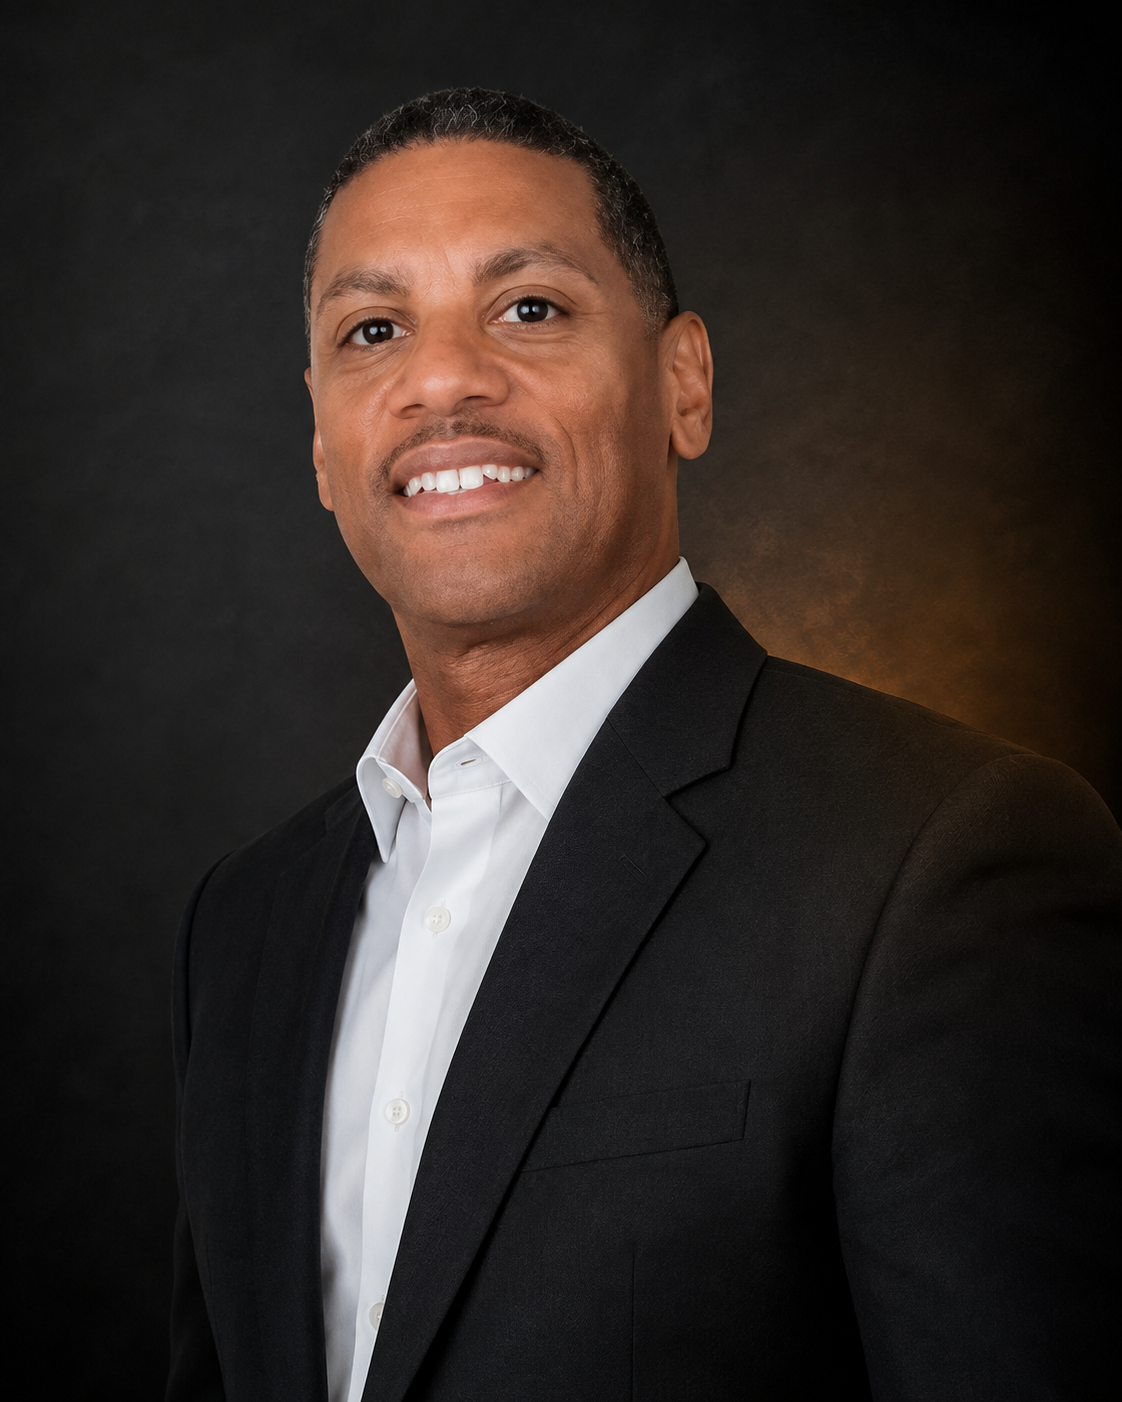
I'm Jesus Escamilla, a licensed Texas insurance agent and independent Life & Health broker. I work across multiple carrier markets and help clients compare health, life, final expense, accident, critical illness, disability-income, and annuity solutions when they fit the problem.
The ABA carrier library helps me examine product verticals, definitions, benefit triggers, limitations, and Texas availability without exposing producer-only materials. I do not believe every risk needs to be insured. Sometimes the right answer is more coverage. Sometimes it is less. Sometimes it is keeping the risk yourself.
Texas LicensedNPN 21020470
IndependentMultiple carrier markets
English / SpanishServing Austin & Texas
Start with what you actually need
Bring the risk. We'll audit the options.
Health, life, income protection, final expense, or retirement income—start with the problem, the budget, and the questions.
AustinRound RockCedar ParkPflugervilleLeanderGeorgetownBudaKyleTexas statewide